

CPOS: Tap to Pay Card Reader
by CPOS
4.4
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 4.4
- Price
- Free
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
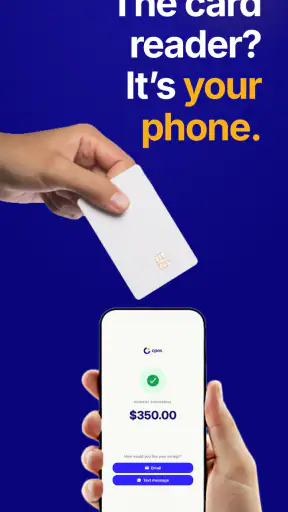
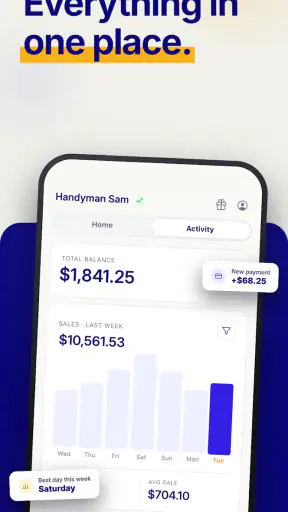
I approached CPOS: Tap to Pay Card Reader as a practical business tool rather than another app I would casually install and forget. Its purpose is straightforward: it lets a compatible phone act as a card reader, so a small business can take payments without carrying a separate reader. That sounds simple, but the real value depends on how smoothly it fits into a repeatable checkout routine.
In my experience, the app makes the most sense for independent sellers, mobile professionals, market stalls, tradespeople, and anyone who occasionally needs to accept a card payment away from a traditional counter. It is a free business app from CPOS, available to users aged Everyone, and its store presence shows a 4.4 average from around two hundred ratings. That gives it a useful level of early reassurance, although I would still test the complete payment flow before relying on it during a busy event.
The app was released in January 2025 and is currently at version 2.34.0, with Android 8.0 or later required. It has passed the ten-thousand-install mark, which suggests that it is not merely a private experiment, while still leaving it feeling more focused than the giant payment platforms many businesses use. The important question is not whether it can replace every checkout system. It cannot. The better question is whether it can remove enough equipment and setup from a particular payment routine to be genuinely useful.
How I would build a reliable everyday checkout routine
I would make reliability a habit rather than something I troubleshoot with a customer waiting: keep a familiar order for preparing the amount, presenting the phone, and checking that the payment has completed. I’d also decide in advance what I’ll do if the phone or connection is unavailable, so the checkout can continue calmly. With that routine in place, the next question is which settings are worth checking before relying on it.
The basic payment flow is best treated as a habit
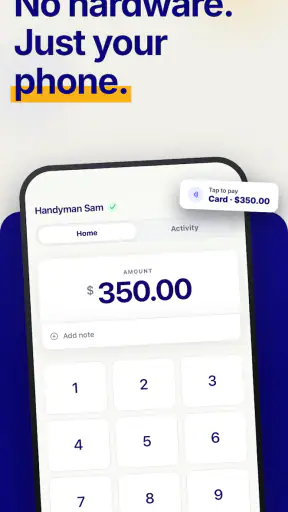
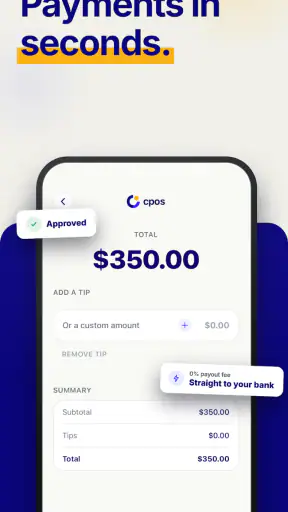
The strongest way to use the app is to make every transaction follow the same sequence. I would open the app before the customer is ready to pay, confirm that the phone has a usable connection and enough battery, enter the amount carefully, and then present the phone for the customer’s contactless card or compatible payment device. After the payment response appears, I would wait for the clear confirmation before moving on to the next customer.
That last pause matters. With a physical reader, the device itself often feels like an obvious authority at the counter. When the phone is doing the work, it is easier to glance away too early or assume that a customer’s tap completed successfully. I found that a consistent visual check is more valuable than trying to rush the final second of a transaction.
For a solo seller, this workflow is particularly appealing because it reduces the number of objects involved. There is no separate reader to remember, charge, protect, and connect. A phone is already part of most mobile work setups, so the payment step can sit alongside messaging, scheduling, navigation, and other daily tasks.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A realistic example would be a photographer collecting a final balance after a short session, or a repair specialist taking payment at a customer’s home. In both cases, carrying a dedicated terminal may feel excessive, but asking for cash or an invoice later adds friction. A phone-based reader gives the customer a direct way to pay while the appointment is still in progress.
Preparation makes more difference than speed
I would not wait until the first customer is standing in front of me to discover how the app behaves on my phone. Before using it professionally, I would open CPOS, explore the payment screen, and run through the available setup steps in a quiet environment. The goal is not simply learning where to tap. It is confirming that the phone is comfortable to hold, that the card-reading area is easy to find, and that the screen remains readable in the lighting where payments will actually happen.
Phone cases deserve attention too. A thick case, wallet attachment, or metal accessory can make contactless interaction awkward even when the phone itself is suitable. I would remove anything that interferes with the customer’s ability to bring a card or device close to the correct part of the phone. This is a small practical detail, but it can prevent the most embarrassing kind of checkout delay: repeatedly asking someone to tap again without knowing whether the problem is the card, the phone, or the positioning.
I would also keep the phone charged before a selling session and avoid using a cluttered home screen as the starting point. The app is free, but the phone remains the central piece of equipment. If it is busy downloading updates, low on power, or constantly interrupted by notifications, the payment experience can feel less dependable than the app itself deserves.
Who benefits most from this approach
CPOS is a natural fit for businesses with occasional or mobile card payments. It is especially attractive when the seller values light equipment more than a large collection of checkout controls. A tutor, cleaner, dog walker, craft seller, pop-up vendor, or independent consultant may only need a clear amount entry and a contactless payment interaction rather than a full retail terminal.
The app is also useful for businesses that already have a main payment system but need a backup method for situations outside the usual workspace. A shop owner attending a local event, for example, may not want to transport the entire counter setup for a small temporary stand. A phone-based option can act as a compact alternative, provided the owner is comfortable with the app’s workflow and the payment conditions at the venue.
I would be more cautious about recommending it as the only checkout tool for a busy store, a business with several employees, or a company that needs detailed inventory, staff permissions, printed receipts, refunds, customer accounts, and end-of-day reporting in one place. In those situations, a conventional terminal or integrated point-of-sale system is usually better because the payment reader is only one part of a much larger operation.
Settings worth checking before the first real transaction
Experienced use begins with checking the app’s available settings rather than assuming the default arrangement is ideal. I would look for every option related to the payment experience, account details, transaction handling, and the way confirmation is shown. Even when there are not many controls, knowing what is available prevents last-minute searching when a customer is waiting.
The amount-entry stage deserves special care. If I am taking several payments in a row, I would make a deliberate habit of reviewing the amount before presenting the phone. A mobile screen gives less physical separation between entering the value and accepting the payment than some countertop systems do. That makes a quick confirmation step essential, especially when prices include decimals or when multiple services have similar names.
I would also decide in advance how I want to handle customer confirmation. If the app provides a completion screen that is easy to show, I would turn the phone toward the customer at the appropriate moment rather than keeping it angled toward myself. If a customer needs proof of payment, I would establish the available way of providing it before the event begins. The important point is to avoid improvising a receipt conversation after the payment has already finished.
Another useful habit is separating payment readiness from general phone use. I would silence unnecessary notifications, close unrelated apps, and keep the CPOS screen easy to reach. This is not a claim that the app includes a special shortcut or kiosk mode; it is a workflow choice I can control myself. A cleaner phone environment makes the payment process easier to explain and reduces the chance of tapping the wrong thing.
Connection and location planning
A phone-based card reader depends on the conditions around the phone. Before taking payments at a market, event, or customer site, I would consider whether the location has dependable mobile data or Wi-Fi and whether the phone can maintain that connection while being used normally. I would not treat the app as a magic solution for areas with unreliable service.
This is one of the most important differences from a traditional checkout arrangement. A dedicated terminal may still depend on connectivity, but it is usually planned as a payment-only device. With CPOS, the same phone may be handling calls, messages, navigation, photos, and other tasks. That makes connectivity and battery management a personal responsibility rather than something delegated to a separate terminal.
For outdoor work, I would prepare a simple fallback: know whether I can accept another payment method, explain the alternative without making the customer repeat the entire checkout process, and keep the phone accessible rather than buried in a bag. The app can reduce equipment, but a professional payment routine still needs a backup plan.
Faster patterns that do not sacrifice accuracy
The fastest users are not necessarily the ones who tap through the screens most aggressively. They are the ones who remove decisions from the moment of payment. I would keep a short price list nearby, group common services into familiar amounts, and decide who enters the total when a customer is paying for several items. This reduces mental switching between conversation, calculation, and the app.
For repeat customers, I would prepare the amount before asking them to tap whenever possible. That makes the interaction feel natural: confirm the service, enter the total, show the payment screen, and let the customer complete the contactless action. The gain comes from a repeatable order, not from inventing a feature the application may not provide.
At a busy stall, I would position the phone so the payment area is obvious and keep the screen at a comfortable angle. I would avoid passing the phone back and forth unless necessary. One person can enter and verify the amount while the customer controls the card or device, which keeps responsibility clear and reduces accidental touches.
A second practical pattern is using a short verbal cue. I might say, “The total is ready; you can tap here,” then wait for the confirmation. That tiny explanation helps customers who are used to a conventional terminal and may not immediately understand that the phone itself is the reader. It also prevents them from tapping the wrong side or holding their card too far away.
For appointments, I would make payment the final step of a fixed closing routine. Finish the work, confirm the total, open CPOS, accept the payment, verify completion, and only then pack away equipment. This is particularly useful for mobile professionals because it stops payment from becoming an afterthought during the transition between customers.
Where the phone-reader model starts to show limits
The main limitation is that CPOS is focused on turning a phone into a card-reading point, not on replacing a complete business-management system. Businesses that need stock control, product scanning, multiple checkout stations, staff activity tracking, detailed sales analysis, or a broad receipt system may find the app too narrow. A traditional point-of-sale package will usually provide a more connected view of the business.
There is also a social limitation. Some customers feel more comfortable paying on a dedicated terminal because its purpose is immediately recognizable. A phone can look personal, and a customer may hesitate if the payment screen is not presented clearly. I found that confidence comes from a clean setup, a visible confirmation, and calm communication. The seller has to make the phone feel like a payment device, not like a personal handset being repurposed at the last moment.
Another trade-off is shared use. If several workers need to accept payments, a single phone-based setup may become inconvenient. Passing one phone around can create confusion, and using personal phones may raise internal questions about consistency and access. For a one-person operation this is barely an issue; for a growing team it can quickly become a reason to choose a dedicated system.
I would also avoid judging the app solely by the promise of avoiding hardware. Hardware-free does not mean responsibility-free. The phone still needs to be compatible with the app’s requirements, maintained, charged, and protected. The business also needs a clear way to reconcile payments with its own records. If the owner expects automatic inventory updates or a complete accounting workflow, this app should be evaluated as one component rather than the whole solution.
How it compares with the usual alternatives
Compared with cash, CPOS can make payment easier for customers who rarely carry notes or coins, while also reducing the need to prepare change. Compared with bank transfers, it keeps the payment conversation at the point of service instead of asking the customer to open another app, enter details, and wait for confirmation. Those advantages are meaningful for small, face-to-face transactions.
Compared with a standalone card reader, the biggest benefit is portability. I do not need to carry another device, and I can keep the payment process close to the rest of my mobile work. The dedicated reader still has advantages, though: it feels more purpose-built, may be easier for multiple staff members to share, and can create a stronger separation between business payments and personal phone activity.
Compared with a full point-of-sale platform, CPOS is simpler and more focused. That simplicity is exactly why I would choose it for a freelancer or occasional seller, but it is also why I would not expect it to manage a complex shop. The right comparison is not “Which system is universally best?” It is “How much checkout infrastructure does this business actually need?”
Questions I would settle before depending on it
Is it really free to install and use? The app is listed as free, which removes an obvious entry barrier. I would still separate the app’s price from any payment-processing terms, account requirements, or business conditions that may apply to accepting transactions. A careful owner should review those practical terms before making the app central to daily revenue collection.
Can it work for every customer? I would not assume that every card, phone, or payment situation will behave identically. The sensible approach is to offer another method when a contactless attempt does not complete and to avoid treating one phone-based workflow as the only possible route. This matters most at events where a failed payment can hold up a queue.
Does it replace a receipt and accounting process? I would treat the payment confirmation as one part of the record, not automatically as a complete bookkeeping system. I would maintain a separate routine for recording sales, matching payments, and handling customer requests for proof. That discipline is especially important for businesses moving away from a more structured terminal.
Is it suitable for a large operation? In my view, it is better suited to an individual or small mobile operation than a multi-counter business. The more people, products, locations, and reporting requirements involved, the more attractive an integrated point-of-sale platform becomes. CPOS earns its place through convenience, not through pretending to cover every business process.
My verdict after using it as a working tool
I like CPOS because it solves a specific problem without asking a small business to begin with a large equipment setup. The phone-based approach is easy to understand, and the free entry point makes it practical to test in a controlled setting. Its strongest quality is not a flashy extra; it is the way it can shorten the distance between finishing a service and accepting payment.
My recommendation comes with a clear condition: build the routine first. Check the phone, prepare the amounts, keep the payment screen easy to reach, verify every completion, and have a backup method ready. Those habits matter more than trying to rush through the interface. Once the process is familiar, the app can feel like a natural part of mobile work rather than an improvised substitute for a terminal.
For a freelancer, occasional seller, or small business that mainly needs contactless payments in person, I think it is worth trying. For a busy retail team or any operation that needs inventory, staff controls, detailed reporting, and a complete checkout ecosystem, I would choose a dedicated or integrated alternative instead. The best use of CPOS is focused, prepared, and mobile: one phone, one clear payment routine, and no unnecessary hardware between you and the customer.
Pros
- Turns compatible phones into a convenient mobile card reader.
- Supports contactless payments without requiring a separate terminal.
- Can help small businesses accept payments while on the move.
- Reduces equipment needs for pop-up shops and service professionals.
- Useful for quick transactions at markets, events, and customer locations.
Cons
- Phone compatibility may depend on NFC support and operating system version.
- Transaction fees or subscription costs may apply depending on the provider.
- Requires a stable internet connection for many payment operations.
- Battery drain can be noticeable during extended payment sessions.
- Payment features and availability may vary by country or merchant account.
FAQs for CPOS: Tap to Pay Card Reader
What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale solution designed to help businesses accept contactless card and digital wallet payments using a compatible smartphone or tablet. Instead of requiring a traditional card terminal, the app can use near-field communication (NFC) technology to process supported tap payments. It is aimed at merchants, independent sellers, service providers, and small businesses that need a portable checkout option.
How does CPOS accept contactless payments?
After setting up a merchant account and completing any required verification, you generally enter the sale amount in the app and ask the customer to tap a compatible contactless card, phone, or smartwatch against the device. The transaction is then authorized through the payment service. Successful use depends on NFC support, internet connectivity, device compatibility, regional availability, and the payment methods supported by the merchant account.
What devices and requirements are needed to use CPOS?
You need a compatible Android or iOS device with NFC capability if tap-to-pay functionality is required, a supported operating-system version, and a reliable internet connection. The device may also need screen-lock protection and other security settings enabled. Requirements can vary by country and payment provider, so checking the app’s current store listing and official compatibility information before downloading is important.
Are there transaction fees or other costs when using CPOS?
Using CPOS may involve payment-processing fees, account charges, or other costs determined by the service provider and your merchant agreement. The application itself may be free to download, but that does not necessarily mean transactions are free. Rates can depend on the card network, payment type, location, currency, and business plan. Review the provider’s pricing, payout terms, refunds, and chargeback policies before accepting payments.
Is CPOS: Tap to Pay Card Reader safe for business transactions?
CPOS is intended to process payments through established mobile payment and card-processing infrastructure, but security also depends on how the merchant protects the device and account. Use the latest app version, keep the phone locked, avoid sharing login details, install updates, and connect through trusted networks when possible. Before relying on the app for regular sales, confirm its supported security features, customer support options, and compliance information.

CPOS: Tap to Pay Card Reader
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@cpos.com, visit https://cpos.com/, or review their https://cpos.com/privacy/.










